Capital Growth vs Rental Yield in Singapore: Which Matters More at Your Stage of Life?
By David Ho · CEA R027577A · · Updated · 10 min read
Capital growth vs rental yield is the trade-off at the heart of every Singapore property you buy to hold: a property can either rise more in value, or pay you more rent each month, and the two rarely come together. As at October 2026, a typical private condo in Singapore rents for roughly 3% of its price a year before costs, so over a decade, growth tends to do more of the heavy lifting. The catch is that growth is a forecast and rent is a fact. Which one you should favour depends less on the property, and more on where you are in life.
Here's how we think it through with clients, with the numbers worked out in full.
Capital growth and rental yield, in plain terms
Capital growth is the rise in your property's value. If you buy at $1,500,000 and sell at $1,800,000, your capital gain is $300,000 before costs. You only collect it when you sell, refinance or right-size.
Rental yield is the rent you earn as a share of the price, each year:
- Gross rental yield = annual rent ÷ purchase price. A $1,500,000 condo renting at $4,000 a month earns $48,000 a year: a 3.2% gross yield.
- Net rental yield = (annual rent − holding costs) ÷ purchase price. Holding costs include property tax, maintenance fees, agent fees, vacancy and repairs. They usually take a third or more of the rent.
Mortgage interest is left out of both, because it depends on how you finance the property rather than on the property itself. We come back to it below, because it decides whether you can hold on.
What the numbers look like in Singapore today
As at October 2026, market estimates put gross yields for private non-landed homes at roughly 3% to 3.5%, a little higher outside the city centre and lower in prime districts. These are indicative: URA publishes price and rent indices, not a yield, so the yield figures come from research houses and portals.
Prices and rents are both still moving. URA's figures for Q3 2026 show private home prices up 1.4% on the quarter and private rents up 1.3%. HDB resale prices, by contrast, slipped 0.1%, their third quarterly dip in a row.
Two points matter more than the headline numbers:
- Yield is visible before you buy. You can check what similar units have actually rented for.
- Growth is not. It depends on what happens to the area, the supply around you and the wider market over the years you hold. Nobody can promise it, including us.
A worked example: two condos at the same price
Two condos, both at $1,500,000. To keep the comparison fair, we use the same maintenance, repairs and financing for both.
- Condo A, growth-led. A newer project near a planned transformation area. It rents for $4,000 a month, and we assume its value grows at 3% a year.
- Condo B, yield-led. An older, larger unit near an established job hub. It rents for $5,000 a month, and we assume 1.5% a year growth, since it is older and has less lease left.
Costs per year, at 2026 non-owner-occupier property tax rates (12% to 36% of annual value, which for a rented home is roughly the annual rent):
| Per year | Condo A (growth-led) | Condo B (yield-led) |
|---|---|---|
| Rent | $48,000 | $60,000 |
| Gross yield | 3.2% | 4.0% |
| Property tax | $7,440 | $10,800 |
| Maintenance fees | $4,800 | $4,800 |
| Agent fees (half a month's rent a year) | $2,000 | $2,500 |
| Vacancy (one month every two years) | $2,000 | $2,500 |
| Repairs and insurance | $1,500 | $1,500 |
| Net rent | $30,260 | $37,900 |
| Net yield | 2.0% | 2.5% |
Now add 10 years of growth at the assumed rates:
| Over 10 years | Condo A | Condo B |
|---|---|---|
| Net rent collected | $302,600 | $379,000 |
| Value after 10 years | $2,015,875 | $1,740,812 |
| Capital growth | $515,875 | $240,812 |
| Total before tax, interest and selling costs | $818,475 | $619,812 |
On these assumptions, the growth-led condo comes out about $199,000 ahead. That's why most long-term wealth in Singapore property has come from capital growth, not rent.
Now change one assumption
Suppose Condo A grows at 1.5% a year too, the same as Condo B. Its capital growth falls to $240,812, and its total drops to $543,412: about $76,000 behind Condo B.
The whole advantage rested on one forecast. That's the honest way to read any growth-versus-yield comparison: the yield side is mostly known, the growth side is a bet. Make sure it's a bet you've thought through, and one you can afford to be wrong about.
The part most comparisons leave out: can you hold it?
Take a $1,000,000 loan over 25 years at 2.6%. The instalment is about $4,540 a month. Net rent covers only part of it:
- Condo A: about $2,520 a month of net rent, leaving roughly $2,020 a month to top up.
- Condo B: about $3,160 a month of net rent, leaving roughly $1,380 a month to top up.
Part of each instalment repays principal, so not all of the top-up is lost: it builds your equity. But it still has to come out of your salary every month, through vacancies, rate rises and the years when you'd rather be spending on your children. At the 4% rate banks use for their stress test, the instalment rises to about $5,280 a month.
Growth only pays the investor who is still holding when it arrives. A property you are forced to sell in a soft year turns a growth plan into a loss.
Which matters more at your stage of life?
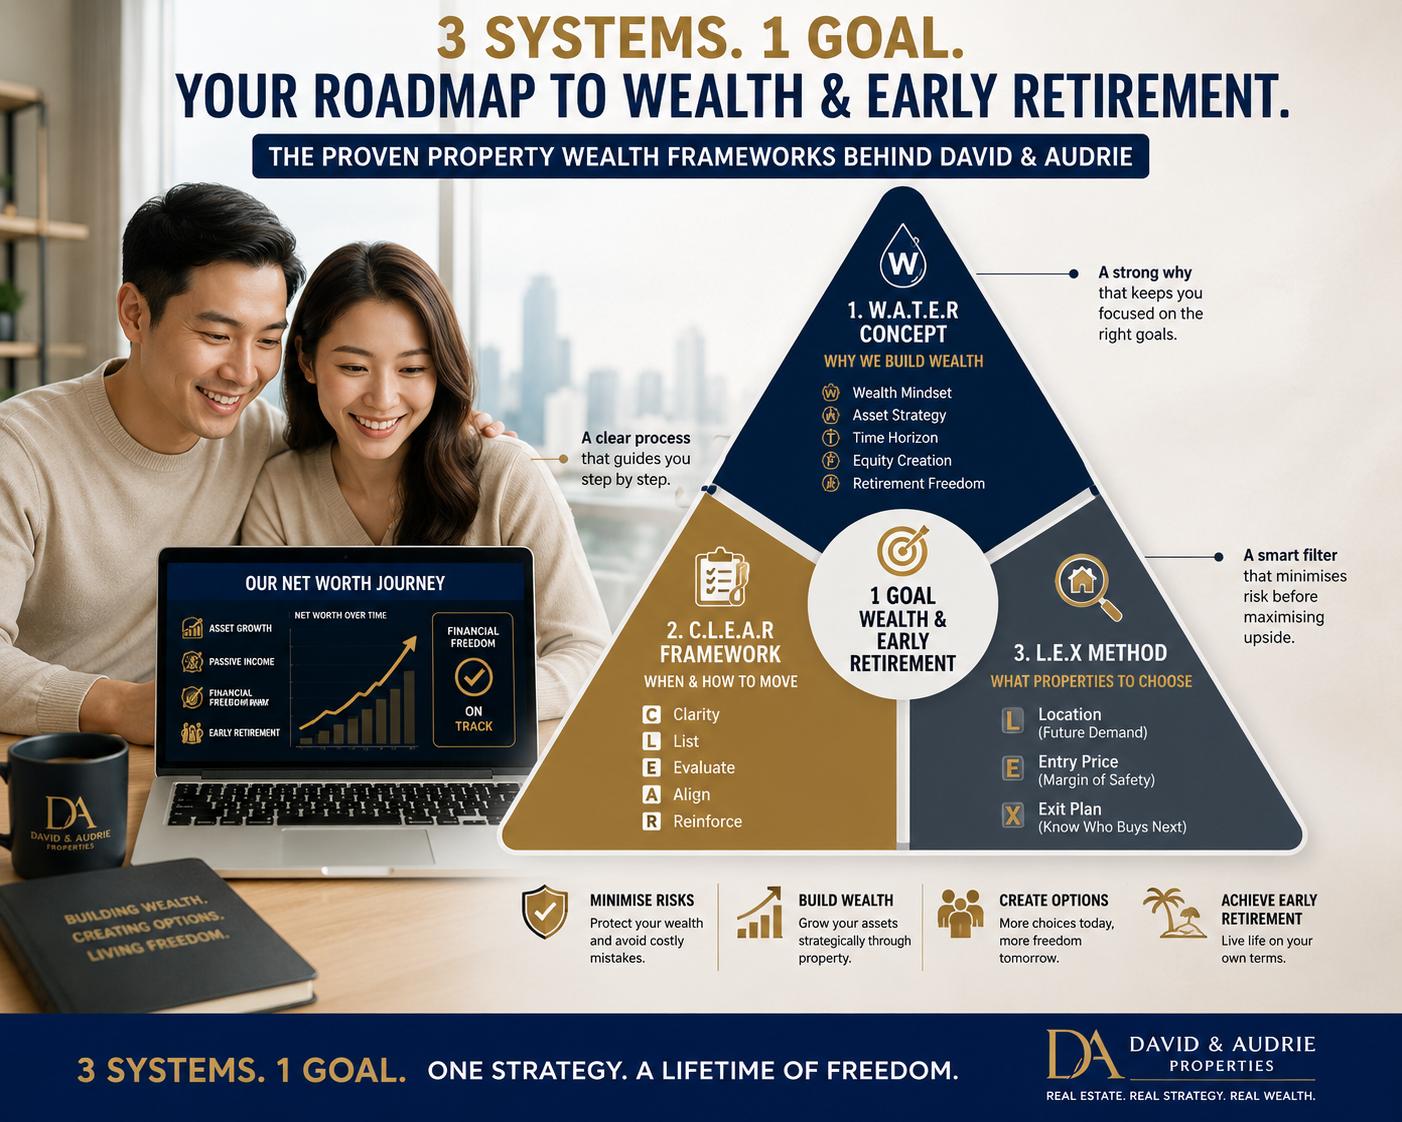
This is where our W.A.T.E.R concept comes in: Wealth Accumulation Towards Early Retirement. W.A.T.E.R asks what a property should do for you over the next 10 to 20 years, then plans backwards from there. Growth and yield are two tools for two different jobs.
| Your stage | Lean towards | Why |
|---|---|---|
| Building years (30s to mid-40s, income rising) | Capital growth | You have time for growth to compound, and your income can absorb a monthly shortfall |
| Consolidating years (mid-40s to 50s) | Balance | Keep growing equity, but reduce how much your salary has to subsidise the property |
| Income years (late 50s onwards) | Rental yield, with lower borrowing | You want cash flow and fewer surprises, and you have less time to wait out a weak market |
Two W.A.T.E.R principles cut across every stage:
- Sequence your purchases so each one strengthens the next. A growth-led home in your 30s can become the equity that funds an income-producing property later.
- Keep flexibility. Don't buy growth you can't hold through a downturn, and don't buy yield in a property that will be hard to sell when you need to.
How to decide, step by step: C.L.E.A.R
Our C.L.E.A.R framework turns the question into five steps you can follow, and explain to your family, before you sign anything.
- Clarity. Write down what this property is for and when you want the money back. Then write the number that matters most: how much a month you can top up for five years without strain.
- List options. Put a growth-led and a yield-led option side by side, at the same budget, plus a balanced middle option. Include resale and post-launch projects, not just what's launching this month.
- Evaluate. Run every option through the same costs, as in the table above. Then run the growth side at half your hoped-for rate, the interest rate at 4%, and the vacancy at three months.
- Align. Check the choice against your stage of life and your family plans: school years, a parent moving in, a career change, the age you'd like to slow down.
- Reinforce. Keep six to twelve months of instalments in reserve. Decide your exit before you buy, and review the plan once a year.
C.L.E.A.R in practice: Daniel and Grace
An illustrative scenario: the names and details are fictional, based on situations we often see with clients.
Daniel and Grace, both 34, earn $30,000 a month together, $15,000 each, and have never owned property. Their plan was a popular one: buy a 5-room resale HDB flat for about $950,000 with Daniel as the owner and Grace as the essential occupier, live in it for the five-year MOP, and then use Grace's name to buy a private condo as an investment. Because Grace wouldn't own the flat, her condo would count as her first property, with no ABSD, and they could keep both homes.
- Clarity. Their real goal was wealth: a property that would grow in value, which they could sell or rent out when their children reach secondary school. The HDB flat was only a stepping stone.
- List options. Plan A: the 5-room flat now, with Grace buying a condo in her own name in five years. Plan B: skip the stepping stone and buy a 4-bedroom condo in the Outside Central Region (OCR) now, together, as their first home.
- Evaluate. Plan A is allowed, and they could keep both properties. But it had two costs that didn't show up on paper. The first was time: five years waiting before the investment even started. The second was price: they'd be buying at whatever prices were then. If OCR prices rose 3% a year, an assumption for illustration only, the same $1,900,000 condo would cost about $2,200,000. And at that point only Grace's income would count for the loan: at the 4% stress rate over 26 years, her $15,000 a month supports a loan of about $1,600,000, short of the $1,650,000 a 75% loan on $2,200,000 would need, and only her own CPF could go into it.
- Align. A 4-bedroom suited the family they're planning. Bought now, together, it's their first property: no ABSD for Singapore Citizens, both incomes count, and it qualifies for the full 75% loan.
- Reinforce. We tested the instalment at 4%, kept a reserve, and agreed the exit before they signed.
| Plan B: 4-bedroom OCR condo | Amount |
|---|---|
| Price | $1,900,000 |
| Loan (75%, 30 years) | $1,425,000 |
| Monthly instalment at 2.6% | $5,705 (19% of income) |
| At the 4% stress rate | $6,803 |
| Buyer's Stamp Duty | $64,600 |
| ABSD | $0 |
| Cash and CPF needed upfront | $542,600 |
What they chose: a 4-bedroom priced below comparable projects nearby, a short walk from an MRT station, in an area with planned growth. It was positioned for exit from day one. 4-bedroom units are what the next upgrader family looks for, and after the four-year Seller's Stamp Duty period they can sell, rent it out or keep it, on their own schedule.
The decision was logical, not emotional. The two-property plan could still have worked, but five years of waiting and prices they couldn't predict might have cut their investment plan short before it began. No one can promise that prices will rise either way, which is why they kept more than $100,000 in reserve after buying.
What drives each one in Singapore
What tends to support capital growth:
- Entry price below comparable projects nearby
- New transport links and regional centres that are funded and dated, not just rumoured
- Limited new supply around you in the years you plan to sell
- Unit sizes and layouts that the next buyer will want
What tends to support rental yield:
- Walking distance to an MRT station and to large employers
- Practical layouts that tenants pay for, rather than dead space
- A lower entry price per square foot, which is often why older projects yield more
- Few competing units for rent in the same project
Our L.E.X method (location, entry price, exit) covers these in detail. A property that scores well on location and entry price often gives you both, a little of each, which is a sound place to start.
To apply these tests to a specific property, see which condo is good for investment in Singapore.
Frequently asked questions
What is a good rental yield in Singapore?
As at October 2026, private condos typically yield around 3% to 3.5% gross, and roughly 2% to 2.5% net after property tax and other holding costs. A gross yield above 4% usually comes with a trade-off, such as an older building, a shorter remaining lease or a less central location. These figures are indicative market estimates, not official statistics.
Is capital growth or rental yield more important?
Over 10 years or more, capital growth has usually built more wealth in Singapore, because yields are modest. But growth is uncertain and only arrives when you sell or refinance. If you need the property to pay its own way, or you're close to the years when you want income, rental yield matters more.
How do I calculate rental yield?
Gross yield is annual rent divided by the purchase price: $4,000 a month on a $1,500,000 condo is $48,000 ÷ $1,500,000, or 3.2%. For net yield, subtract property tax, maintenance, agent fees, vacancy and repairs from the rent first, then divide by the price.
Do I pay tax on rental income in Singapore?
Yes. Rental income is added to your other income and taxed at your personal rate. IRAS lets you deduct either your actual expenses or a deemed 15% of the gross rent, plus mortgage interest. Check the IRAS guidance for your own situation, or ask a tax adviser.
What this means for you
If you're early in your career with room in your budget, a growth-led property you can comfortably hold is usually the stronger long-term choice. If you're closer to the years when you want income, the rent you can see often matters more than the growth you hope for. Most families end up somewhere in between, and that's fine, as long as the choice is deliberate.
If you'd like to put your own numbers through this comparison, we can work through a buying plan with you, or start with our affordability calculator. For the longer view, see how we plan a property portfolio across life stages.