Bidadari HDB Flats Reaching MOP: Million-Dollar Resales, and What to Do Next
By David Ho · CEA R027577A · · 4 min read
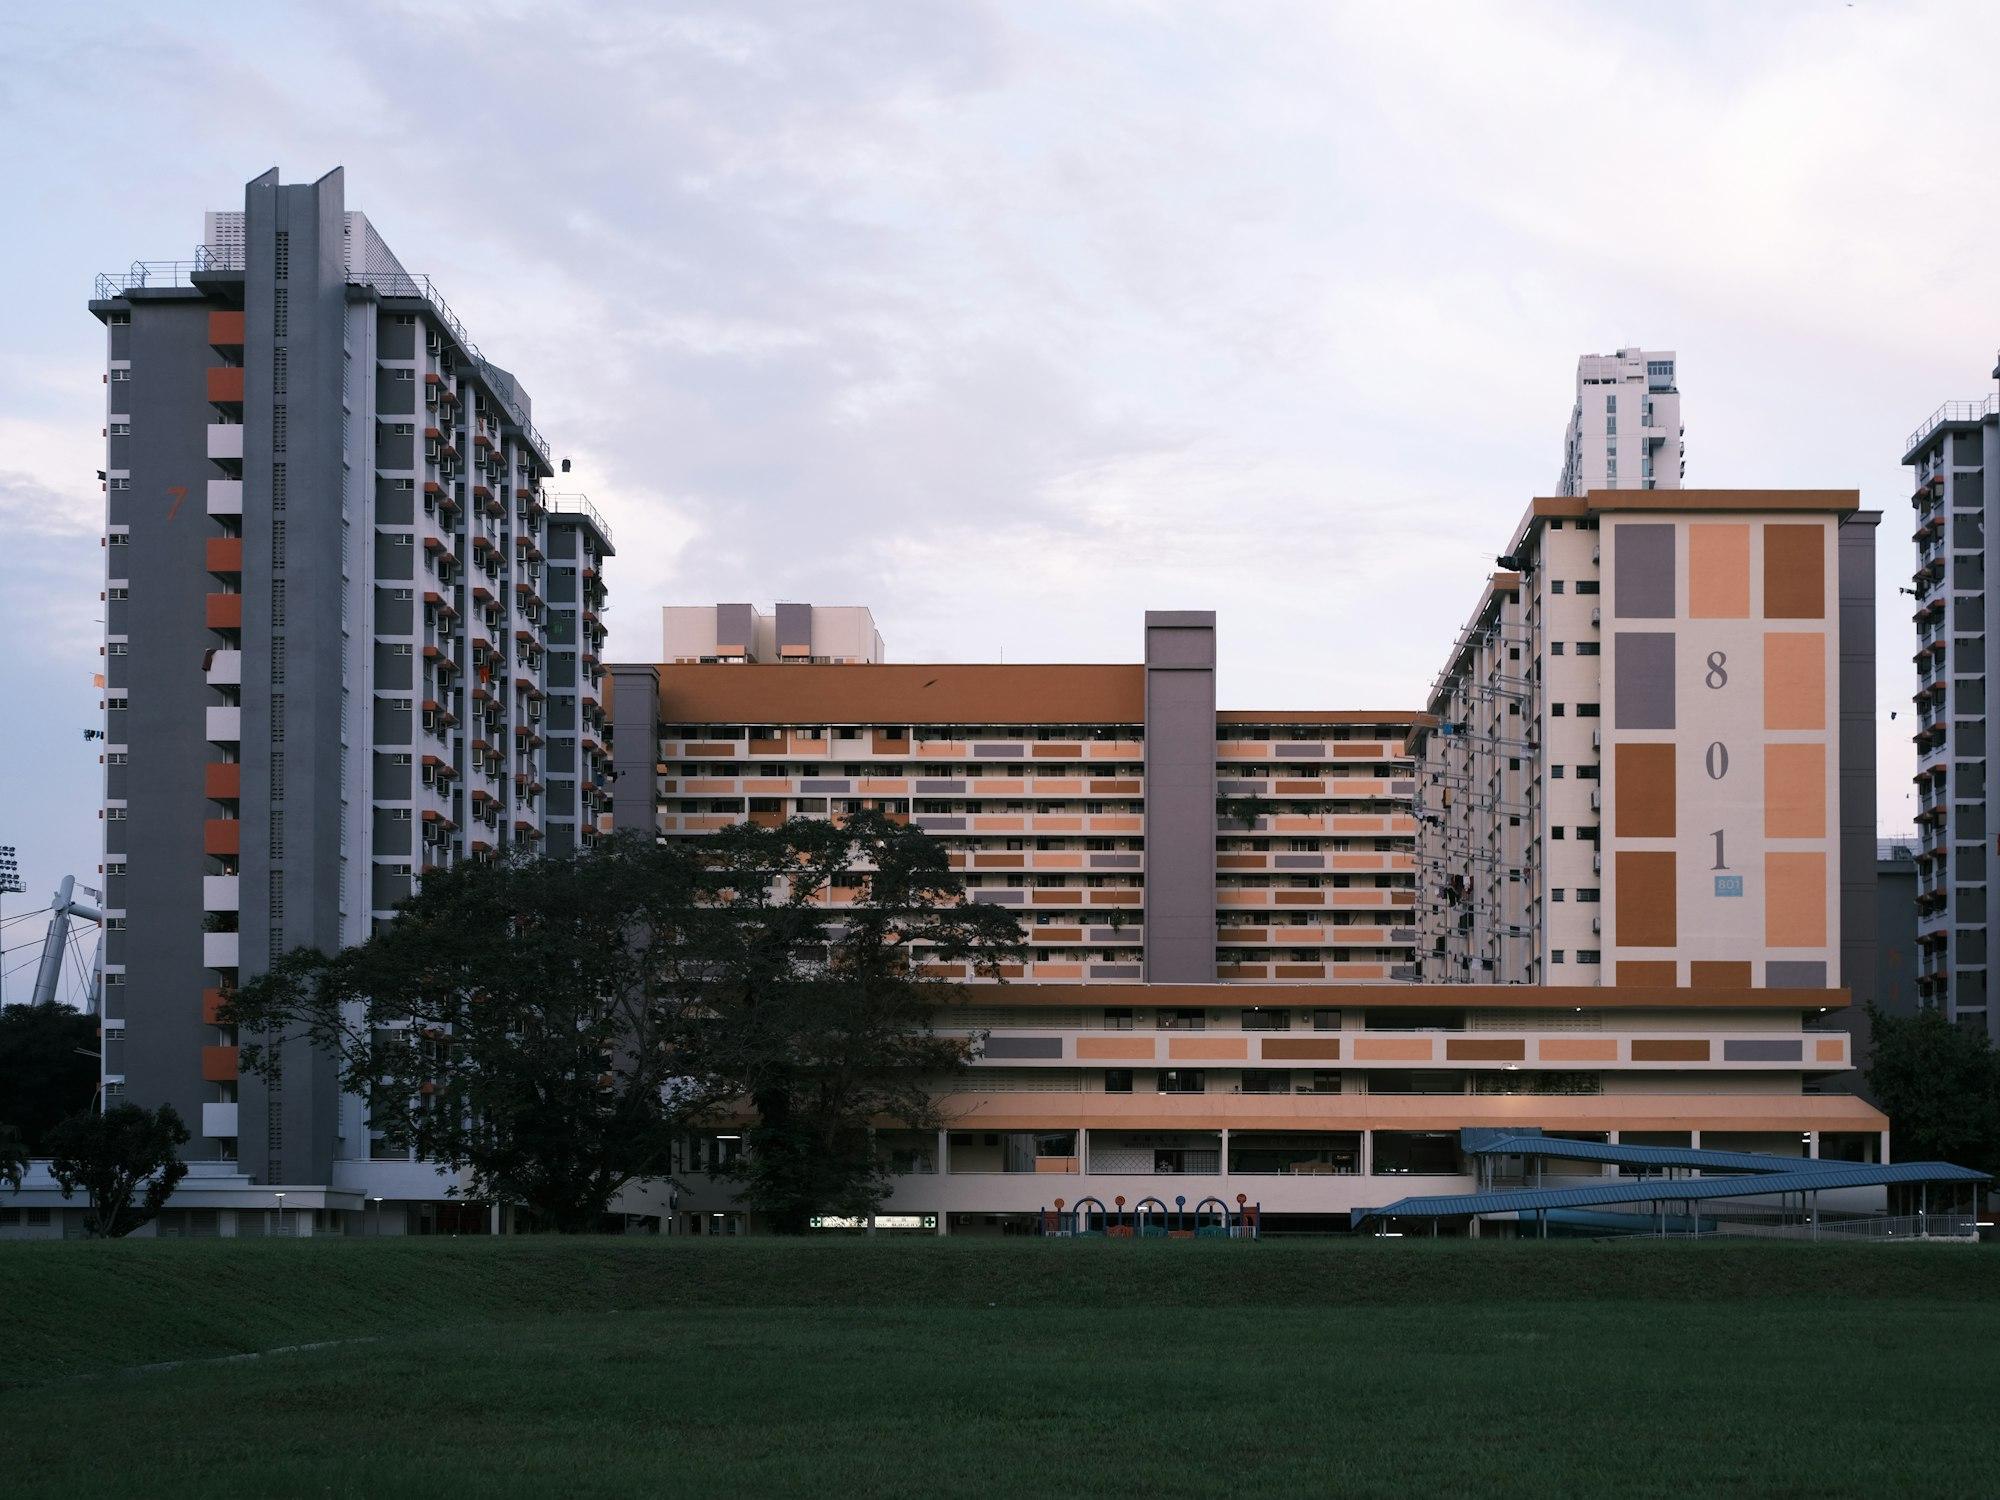
Bidadari's newer flats have become some of the most valuable HDB homes in Singapore. Flats completed in 2021 at Bidadari Park Drive and Alkaff Crescent reached their MOP in 2026, and 4-room flats there have resold at a median of about $1,080,000. About 2,000 more flats, at Woodleigh Link and Bidadari Park Drive, reach MOP in 2027. For these owners, the risk isn't selling too cheaply. It's letting a large windfall turn into a larger loan.
This guide lists the Bidadari blocks, shows what they're selling for, and sets out how to decide. All figures are from HDB's data, as at October 2026.
Which Bidadari flats reach MOP, and when?
Your MOP is five years from the day you collected your keys. HDB's records show when each Bidadari block was completed:
| Expected MOP | Street | Blocks | Flats |
|---|---|---|---|
| 2025 to 2026 | Bidadari Park Drive | 101A to 104A | 1,258 |
| 2026 | Bidadari Park Drive | 107A to 110B | 837 |
| 2026 | Alkaff Crescent | 111A to 114B | 757 |
| 2027 | Woodleigh Link | 201A to 208A | 1,330 |
| 2027 | Bidadari Park Drive | 213A to 215A | 676 |
Check your own date on the HDB Flat Portal, under My Flat Dashboard.
What Bidadari MOP flats sell for in 2026
HDB's resale records for January to October 2026:
| Street (lease from) | Flat type | Resales | Median | Range |
|---|---|---|---|---|
| Bidadari Park Drive (2021) | 3-room | 35 | $815,888 | $710,000 to $868,000 |
| Bidadari Park Drive (2021) | 4-room | 91 | $1,088,000 | $967,000 to $1,280,000 |
| Bidadari Park Drive (2021) | 5-room | 8 | $1,465,000 | $1,378,888 to $1,490,000 |
| Alkaff Crescent (2021) | 4-room | 34 | $1,079,000 | $900,000 to $1,200,000 |
| Alkaff Crescent (2020) | 4-room | 23 | $1,088,888 | $965,000 to $1,368,000 |
| Bidadari Park Drive (2020) | 4-room | 10 | $1,130,444 | $970,000 to $1,200,000 |
Of the 101 4-room resales at Bidadari Park Drive in 2026, 94 were at $1 million or more. Within the same street, though, prices differ by over $300,000, mostly because of floor level, views over the park and distance to the MRT.
The real risk: a bigger loan, not a lower price
When a flat sells for more than a million dollars, the bank will often lend you a great deal more. That's where families get into trouble. A larger budget feels like a reward for having bought well, but the instalment on the next home is paid every month for 25 years or more.
C.L.E.A.R in practice: Marcus and Jia Wen
An illustrative scenario: the names and details are fictional, based on situations we often see with clients.
Marcus and Jia Wen, both 40, earn $16,000 a month together. Their Bidadari Park Drive 4-room reached MOP this year. Their friends assumed they'd move "up" to the biggest condo they could get.
- Clarity. They wanted a third bedroom and a home near their children's schools, and to keep building wealth for an earlier retirement.
- List options. A condo at their ceiling, a condo well below it, or staying in a central flat that has already done well for them.
- Evaluate. Selling at the median, $1,088,000, would return $280,000 to their CPF and $481,282 in cash. Our HDB upgrade calculator put their ceiling at about $2,181,000 if they sold first, with an instalment of $7,421, 46% of their income. Buying first would have allowed only about $180,000.
- Align. A $1,800,000 condo kept the instalment at $6,125, 38% of income, over a 25-year loan, and left about $388,700 in reserve.
- Reinforce. They tested the instalment at 4% ($7,126) and kept the reserve for the children's education and their own retirement.
| $1,800,000 condo | Their ceiling, $2,181,000 | |
|---|---|---|
| Monthly instalment at 2.6% | $6,125 (38% of income) | $7,421 (46% of income) |
| Buyer's Stamp Duty | $59,600 | Higher |
| Cash and CPF left after buying | About $388,700 | Much less |
The ceiling was the emotional pull. A home that fits, with a reserve that keeps their retirement plan on track, was the logical answer. Staying put was a sound option too: under our W.A.T.E.R concept, a central flat that has grown in value can keep doing its job.
How to plan: C.L.E.A.R
- Clarity. Your finances, goals, needs and choices, starting with what your sale really frees up after the loan and CPF refund.
- List options. Upgrade, right-size within Toa Payoh, or stay.
- Evaluate. Price your flat from your own block and stack. Decide the order: sell first or buy first.
- Align. Set a budget from what you're comfortable paying each month, not from the bank's ceiling.
- Reinforce. Keep a reserve, and plan where you'll stay between homes.
Frequently asked questions
Which Bidadari flats reach MOP in 2026?
Mainly the flats completed in 2021 at Bidadari Park Drive (Blocks 107A to 110B) and Alkaff Crescent (Blocks 111A to 114B), about 1,600 flats. Blocks 101A to 104A, completed in 2020, reached MOP from 2025.
How much is a Bidadari 4-room flat worth in 2026?
Between January and October 2026, 4-room MOP flats at Bidadari Park Drive resold at a median of $1,088,000, between $967,000 and $1,280,000. At Alkaff Crescent, the median was about $1,079,000.
Which Bidadari flats reach MOP in 2027?
About 2,000 flats completed in 2022, at Woodleigh Link (Blocks 201A to 208A) and Bidadari Park Drive (Blocks 213A to 215A).
Should I sell my Bidadari flat now that it's worth over $1 million?
Only if the move serves your family's plans. A high sale price also means a high price for the next home. Many owners do best by setting a budget well below what the bank will lend, or by staying in a central flat that suits them.
What this means for you
A Bidadari MOP flat is a rare opportunity: a young, central flat that has gained a great deal of value. Use it to strengthen your family's long-term plan, not just to buy a bigger home.
If you'd like a plan built around your block and your numbers, we can help you sell your HDB flat and line up the next home.